|
Friends, Twenty years ago, my wife and I (Stoffel, here) were both teaching at public charter schools in Washington, DC. They couldn't have been more different: mine was extremely regimented; hers was more free-flowing. Mine was squarely focused on academics; hers on the whole child. By and large, we both agree that mine performed much better. But it wasn't because the regimented academic focus is better. It was because my school had a crystal clear mission; hers didn't. Our mission: to get our students to and through college. That was it. And every decision we made in teacher meetings was guided by this compass. The parents knew what they were signing up for; and we largely delivered on that promise. Mission statement in your own lifeYou've probably heard us talk a great deal about why we think company mission statements are so important. The story above was the genesis of that focus. But today, I want to talk about something even more vital: mission statements in your own life. My wife and I set off to create a mission statement for our family a number of years ago. What we landed on: to nurture meaningful connections. Thus far, it has stuck around for almost six years. But a funny thing has happened. We've learned as we applied it. For instance, just after our son was born, we had a wedding to attend in Mexico. Should we travel there with a newborn? Well, yes: it was nurturing our connection with the couple getting married. What a lesson that was: while the wedding was great, everything outside of it was a headache. When we returned from Mexico, he vowed never to do that again. The lesson: while our relationship with the couple was important, our relationship with ourselves was more important. We sacrificed the latter for the former and paid the price. Missions in our money livesWhich brings us to a recent money decision we had to make in our own lives. Our daughter is now in middle school, and we live right across from the school. Before, our house was an every-once-in-a-while hangout place. Now, it feels like there's a steady stream of visitors. We're happy to help our daughter to connect with others, but there isn't enough hangout space for everyone without my wife and I retreating to our room. So we decided to finish our basement. But to do so, we had to break a money rule. Usually, we keep a minimum of three months of expenses in cash. We will now use that money for the basement. We do have an undrawn HELOC to provide flexibility if we need it, but it feels odd (and a bit hypocritical) for us to be doing this. I spent much of the last 15 years of my life writing about why decisions like this aren't wise. But when you have two children aiming to nurture their meaningful relationships, and you can pull it off by breaking a money rule that won't be fatal, the math starts to change. I know we'll build our savings back up. When I'm on my deathbed, I don't think I'll regret working to give our kids the chance to connect with others in a safe space. And I'm thankful we had a mission in place to help us make these types of long-term decisions. Wishing you investing success, |
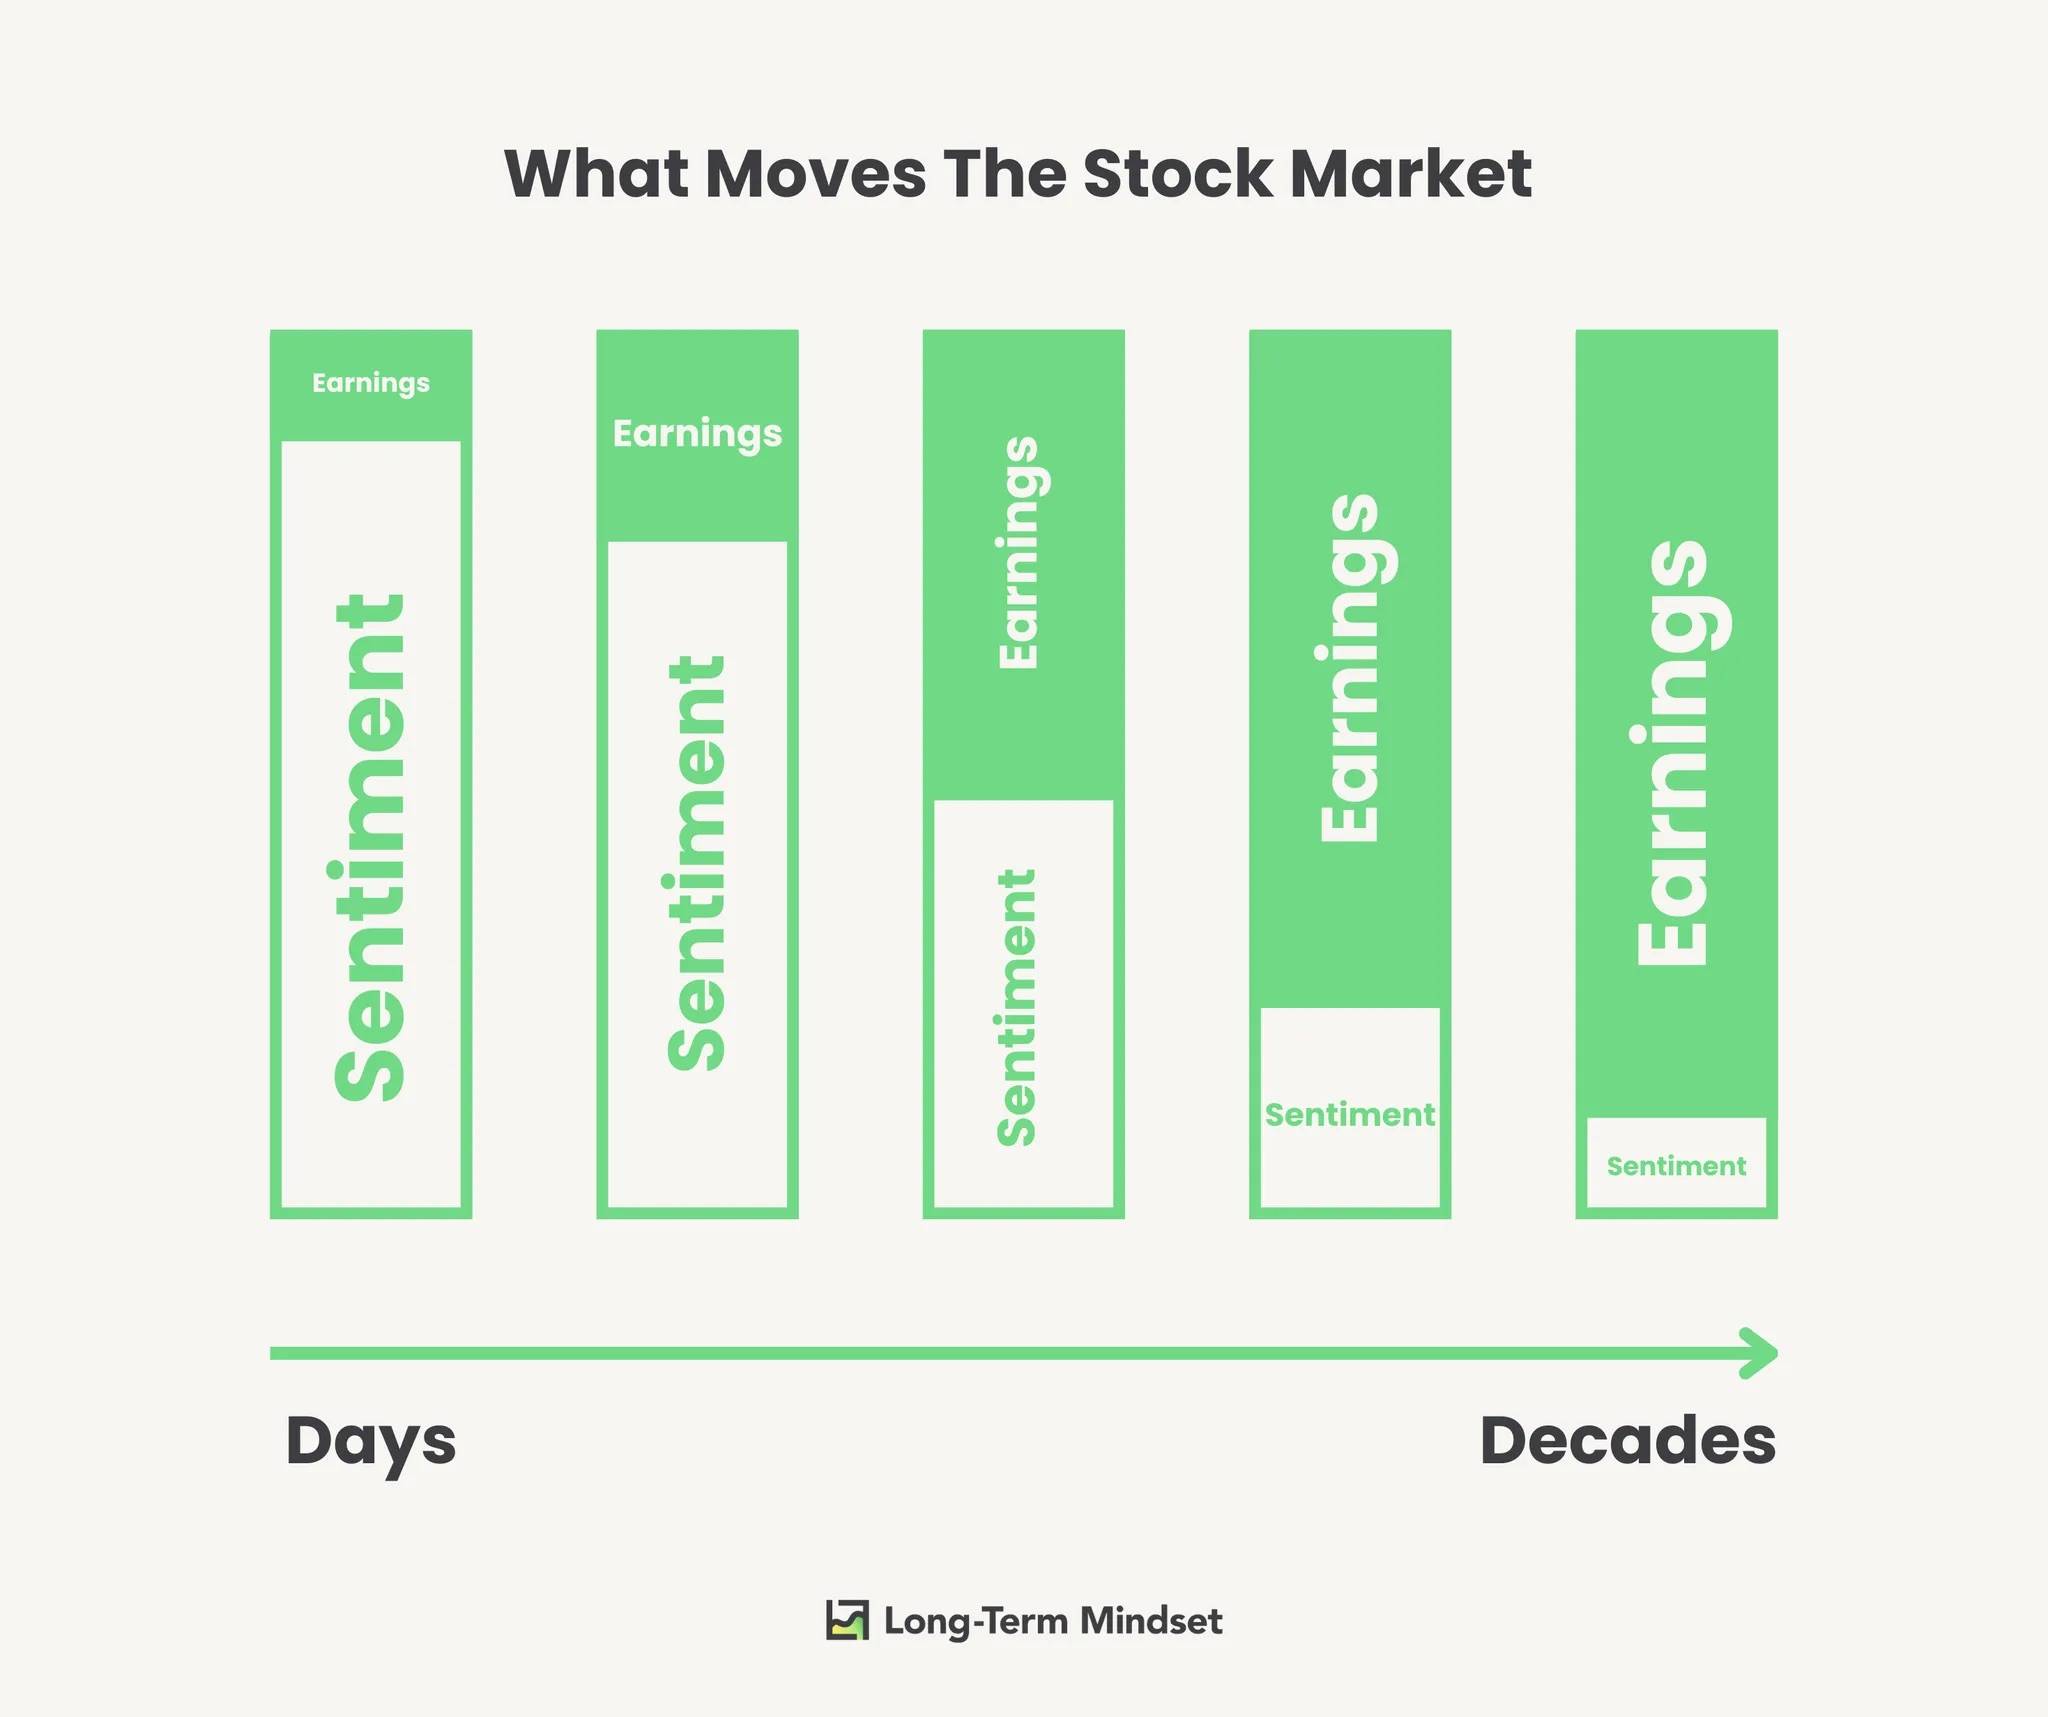
One simple graphic |
One piece of timeless contentOur subscribers are great savers and live within a spending budget. But there's an argument to be made that some of your hard-earned money should be spent "foolishly." Check out Nathan Barry's interview with Will Guidara who lives by the 95/5 rule. |
One resourceWith the threat of AI taking jobs, Ben Carlson, a Ritholtz Wealth Portfolio Manager, looks to timeless career advice from Jerry Seinfeld. |
One Stock DiveWe used Stock Simplifier to make this one-page overview of Airbnb (NASDAQ: ABNB). To make a one-page overview of any stock, simply rate each category, and the download button will appear. |
One quote |